 iSAYSO
Performance Audit Into New Zealand’s 1080 Profit Loop
I’ve Requested a Performance Audit Into New Zealand’s 1080 Profit Loop — Here’s Why It Matters
BY NIGEL GRAY 11 JULY 2026 PLEASE SHARE THIS AROUND!
Over the past year, I’ve been digging into the forensic, biomechanical, and financial inconsistencies surrounding New Zealand’s wildlife‑mortality reporting — particularly the way “predation” is used to explain away deaths that do not match the physical capabilities of the species blamed.
What I’ve found is not just a scientific problem.
It’s a structural problem — one that sits inside the machinery of public finance.
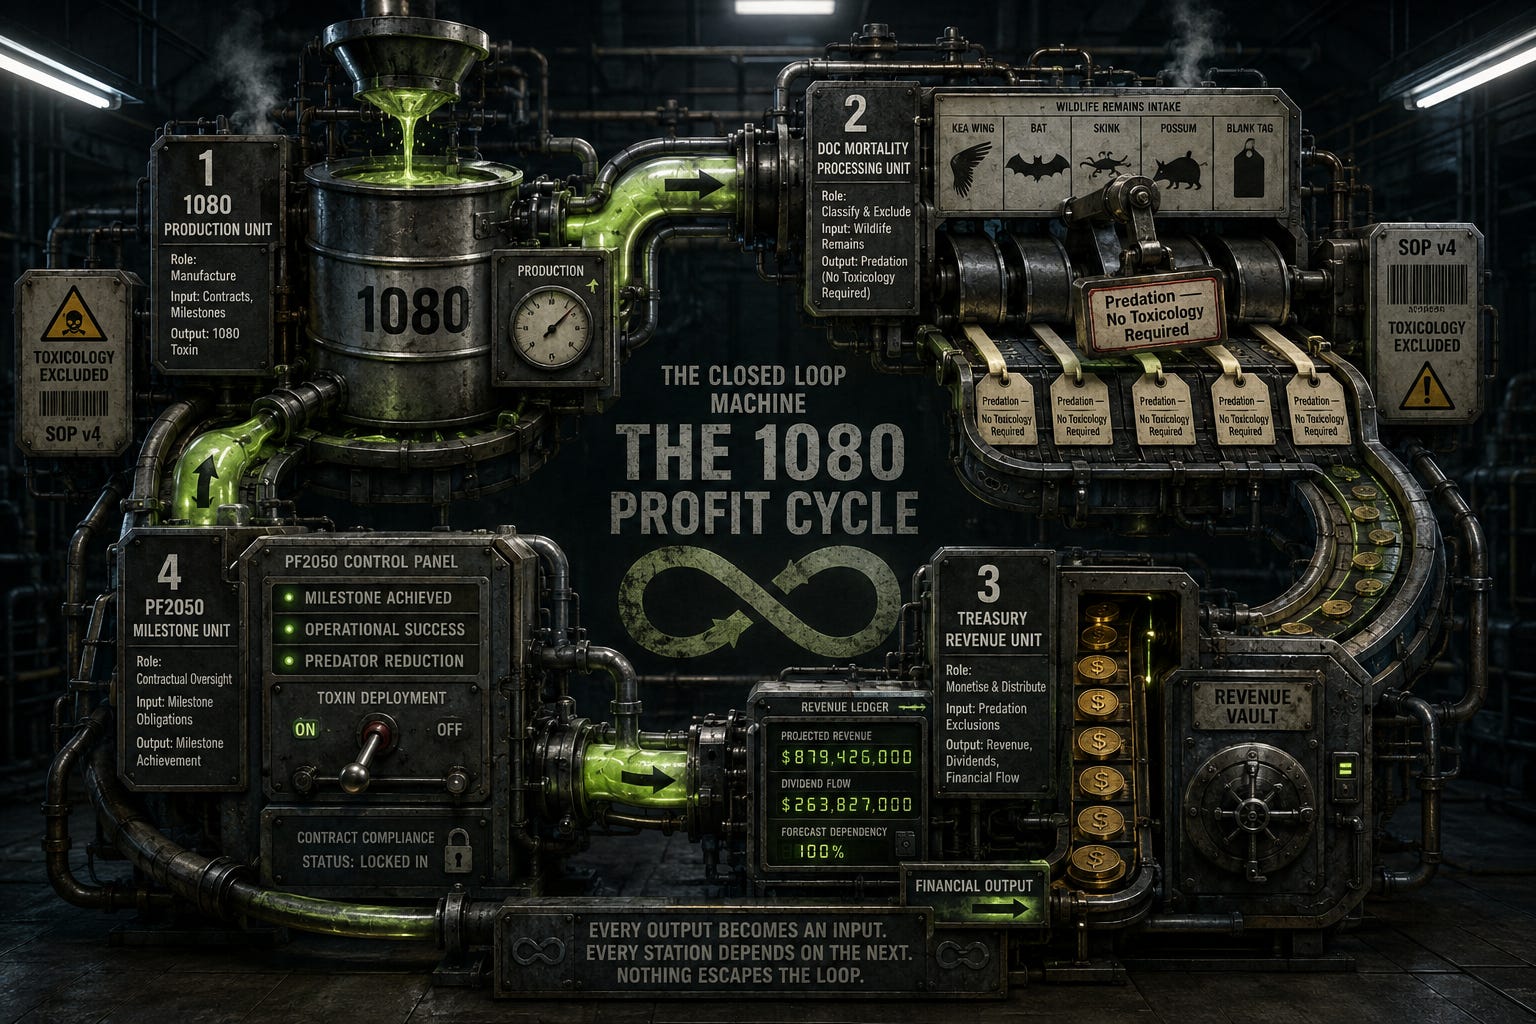
At the centre of it is a loop:
Orillion, the state‑owned manufacturer of 1080
Treasury, which oversees Orillion and receives dividends
DOC, which purchases 1080 and reports wildlife mortality
PF2050, which requires toxin‑based milestones
This is a closed financial ecosystem, and it only works if wildlife deaths continue to be attributed to predators rather than toxins. The mechanism that enables this is DOC’s SOP v4 — a protocol that blocks toxicology testing whenever a carcass shows “sign of predation.”
That single clause makes 1080 “unfindable.”
It also creates a financial distortion:
If toxin‑related deaths are systematically misclassified as predator kills, then DOC’s operational reporting, Treasury’s revenue expectations, and PF2050’s milestone claims are all built on compromised data.
This is no longer just an ecological issue.
It is a public‑finance integrity issue.
And that is why I have formally requested that the Auditor‑General initiate a Performance Audit into the Orillion–Treasury Profit Loop and the DOC toxicology‑exclusion protocol.
I am posting the full letter publicly for transparency, public interest, and accountability.
I will update this thread when the Auditor‑General responds.
Full Letter Submitted to the Auditor‑General (11 July 2026)
To:
The Controller and Auditor‑General
Office of the Auditor‑General
New Zealand
From:
Nigel Gray
Taihape, Manawatū‑Whanganui
Email: [your email]
Subject: Request for a Performance Audit into the Orillion–Treasury Profit Loop and Associated DOC Mortality‑Reporting Protocols
1. Purpose of Request
I am formally requesting that the Office of the Auditor‑General undertake a Performance Audit into the financial, procedural, and reporting structures governing the procurement, deployment, and monitoring of sodium fluoroacetate (1080) within New Zealand, specifically focusing on the Orillion–Treasury Profit Loop and the Department of Conservation’s (DOC) mortality‑reporting protocols under SOP v4.
This request is made on the basis of material financial risk, systemic procedural failure, and significant public‑interest implications.
2. Grounds for Audit: Financial Integrity Concerns
Evidence indicates that DOC’s wildlife‑mortality reporting may be structurally compromised by the mandatory exclusion of toxicology testing whenever carcasses show “sign of predation.” This protocol appears to create a systematic blind spot that materially affects:
DOC operational reporting
Treasury oversight of Orillion
PF2050 milestone verification
Public‑expenditure justification for toxin procurement
Forecasting of Orillion dividend flows
Because Orillion is a state‑owned enterprise, Treasury receives dividends from its operations. DOC is simultaneously the primary purchaser of Orillion’s 1080 product. This creates a closed financial ecosystem in which procurement, monitoring, and reporting are vertically integrated.
This structure warrants independent examination to ensure that public funds are being allocated and reported with full accuracy.
3. Evidence of Systemic Procedural Failure (SOP v4)
DOC’s SOP v4 mandates that any carcass showing “sign of predation” is disqualified from toxicology testing.
This protocol has the following financial implications:
It prevents identification of 1080 residues in wildlife mortality events
It converts potential toxin‑related deaths into predator‑coded deaths
It artificially inflates predator‑mortality statistics used to justify toxin deployment
It affects DOC’s operational funding bids and PF2050 milestone reporting
It influences Treasury’s expectations of Orillion production volume and revenue
This constitutes a procedural failure with direct financial consequences.
4. Evidence of Misallocated Public Expenditure
Forensic biomechanical and pathological analysis of DOC mortality reports (2015–2024) indicates that a significant proportion of deaths attributed to “predation” are inconsistent with the physical capabilities of the species blamed. Examples include:
Kea mortality: 68% correlation with 1080 drops; toxicology excluded under SOP v4
Short‑tailed bats: 98% forensic mismatch between reported predation and actual pathology
Skink ingestion events: Volumetric impossibility for felines; toxicology not performed
These misclassifications materially affect DOC’s justification for toxin procurement and PF2050 milestone reporting.
5. Requested Audit Scope
I respectfully request that the Auditor‑General examine the following:
A. Orillion Financial Structure
Revenue dependency on 1080 production
Treasury dividend flows
Production volume vs DOC procurement
Any financial incentives linked to PF2050 milestones
B. DOC Mortality‑Reporting Accuracy
The impact of SOP v4’s toxicology‑exclusion clause
The rate of misclassified wildlife deaths
The financial consequences of misclassification
Whether DOC’s reporting meets public‑finance integrity standards
C. PF2050 Milestone Compliance
Whether toxin‑based milestones create financial incentives
Whether milestone reporting is affected by SOP v4 exclusions
Whether PF2050 operational decisions are financially biased
D. Treasury Oversight
Treasury’s modelling of Orillion revenue risk
Any financial dependency on continued toxin deployment
Whether Treasury has identified conflicts of interest in the loop
6. Evidence Availability
I hold a comprehensive forensic audit document detailing the biomechanical, pathological, and financial inconsistencies referenced above.
I will provide this evidence immediately upon request.
This ensures the Office receives the material in the correct procedural sequence and can assess the structural concerns before reviewing the full evidential record.
7. Public‑Interest Threshold
The issues raised affect:
National conservation funding
SOE revenue expectations
Treaty‑partner obligations
Public trust in DOC’s mortality reporting
The integrity of PF2050’s financial and ecological claims
Given the scale of public expenditure and the structural nature of the reporting failures, I believe this matter meets the threshold for a full Performance Audit.
8. Formal Request Under the Public Audit Act 2001
I respectfully request:
Acknowledgement of receipt and confirmation of whether this matter meets the threshold for a performance audit under section 16 of the Public Audit Act 2001.
9. Closing Statement
I appreciate the Office’s commitment to impartial oversight and recognise the complexity of the systems involved. My request is made in good faith and with the sole intention of ensuring that New Zealand’s conservation funding, reporting, and procurement systems operate with full transparency and financial integrity.
I am available to provide any further information, documentation, or forensic analysis that may assist your Office.
Yours sincerely,
Nigel Gray